

Interswitch wants Nigerians to trust tap-to-pay
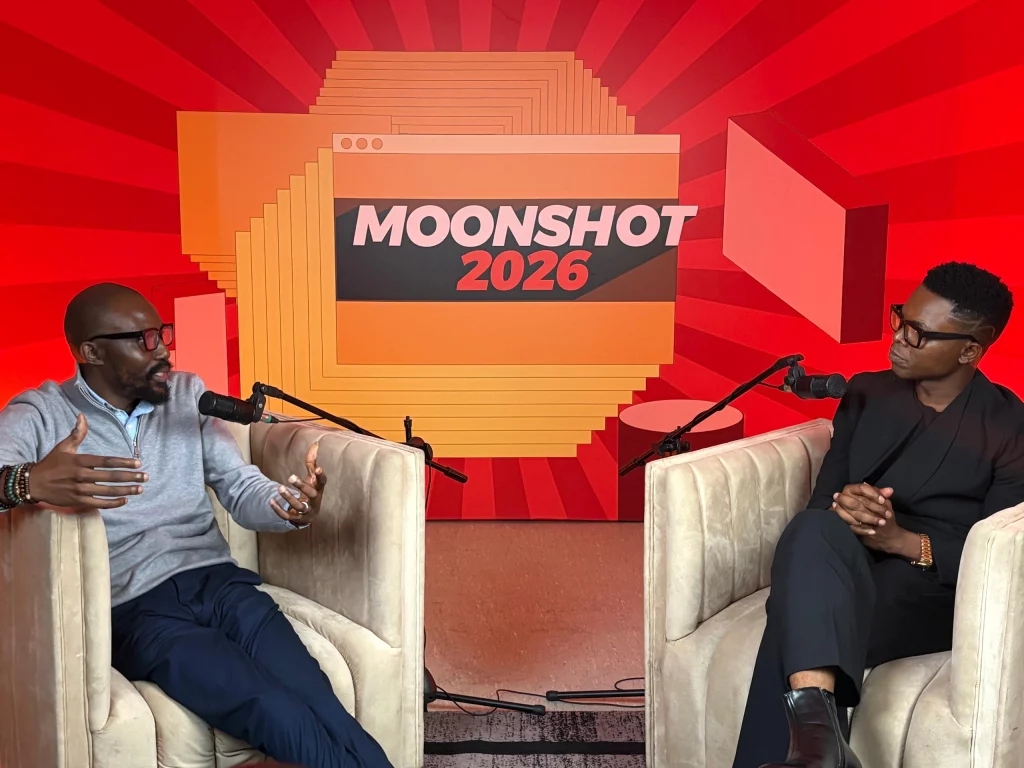
Interswitch, a Nigerian payments technology company, says consumer education is the biggest hurdle to making tap-to-pay a mainstream payment method in Nigeria, even as banks and merchants prepare to support it. Speaking at Moonshot 2026 in Lagos on Thursday, Tomi Ogunlesi, divisional head of brands, communication, content and CSR at Interswitch, said the industry must convince consumers that tapping their cards or phones to pay is secure and convenient.
“The banks are ready,” Ogunlesi said. “Where more of the work needs to be done now, from our perspective as an industry, is on the merchant side and on the consumer side, but most on the consumer side.”
His comments come after Mastercard and Interswitch announced the launch of Google Pay in Nigeria, allowing eligible Mastercard holders to add their cards to Google Wallet and pay with compatible Android phones at contactless-enabled terminals. Interswitch’ said that it was working with five Nigerian banks, including GTBank, Wema Bank, ProvidusUnity Bank, Zenith Bank, and FirstBank, to expand tokenised tap-to-pay transactions. The company said it is also working to bring more merchants into the network, including supermarket chain, Spar, had shown interest.
Contactless payments are not new to Nigeria. In 2015, Unified Payments launched PayAttitude, an NFC-based payment service, with several Nigerian banks. It used a chip-enabled tag attached to a mobile phone or another surface to make payments at compatible terminals.
A decade later, Access Bank partnered with Visa in March 2025 to launch Tap to Phone, which turns an NFC-enabled Android smartphone into a payment terminal for merchants accepting contactless card payments. In October, CashAfrica, a Nigerian contactless payments infrastructure startup, also partnered with Chicken Republic to bring mobile tap-to-pay to more than 350 outlets.
Despite these attempts, tap-to-pay has yet to become a mainstream payment method in Nigeria. Infrastructure gaps and limited consumer awareness have made it difficult for contactless payments to gain widespread adoption. Interswitch has now taken up the challenge to persuade consumers to use the technology.
Ogunlesi said Interswitch had anticipated the shift towards tokenised payments by making most of the cards it issued over the past two to three years compatible with the technology. However, he acknowledged that the simplicity of tap-to-pay could itself make some Nigerians suspicious. Ogunlesi said consumer education must explain how tokenisation protects payment details.
“At its core, tokenisation means your card details have gone through a process where the token that is replacing your card number in a tap-to-pay transaction is not your card number,” he said. “It’s more like a one-time token that is being used to mask your card number.”
Interswitch plans to support sensitisation efforts with a 15-minute documentary titled ‘Are You Tapping?,‘ which explores the evolution of payments in Nigeria and explains why tokenisation matters.
In a separate conversation at Moonshot, Ogunlesi said Nigeria embraced card payments earlier than some other African markets, where mobile money services helped drive the growth of digital payments. He pointed to Interswitch’s experience in 2009, when the Central Bank of Nigeria ordered the shutdown of magnetic-stripe cards amid fraud concerns. It forced the industry to transition towards EMV chip cards, creating an opportunity for Verve, Interswitch’s domestic card scheme.
He also argued that cards retain an advantage in areas such as international commerce and dispute resolution, where established card networks have developed processes for handling failed transactions and recovering funds. Bank transfers may work well for domestic payments, but resolving disputes involving cross-border transactions can be more complicated. He expects the physical form of cards to change as payments become digital, but believes the underlying infrastructure will remain important.
“Cards are what everybody is trying to disrupt,” he said. “But the interesting thing is that even the things that are going to disrupt cards run with the DNA of cards.”
Ogunlesi identified card rails, non-card rails such as instant bank transfers, and digital-asset rails as three broad areas of payment infrastructure that could support faster or cheaper cross-border transfers. He said Interswitch was exploring how digital-asset infrastructure could be developed in ways that are trusted and compatible with regulatory requirements. However, the company’s immediate priority is getting more Nigerians comfortable with tapping to pay.
Crédito: Link de origem