

EBRD targets Benin SME bankability with advisory support and new financing tools
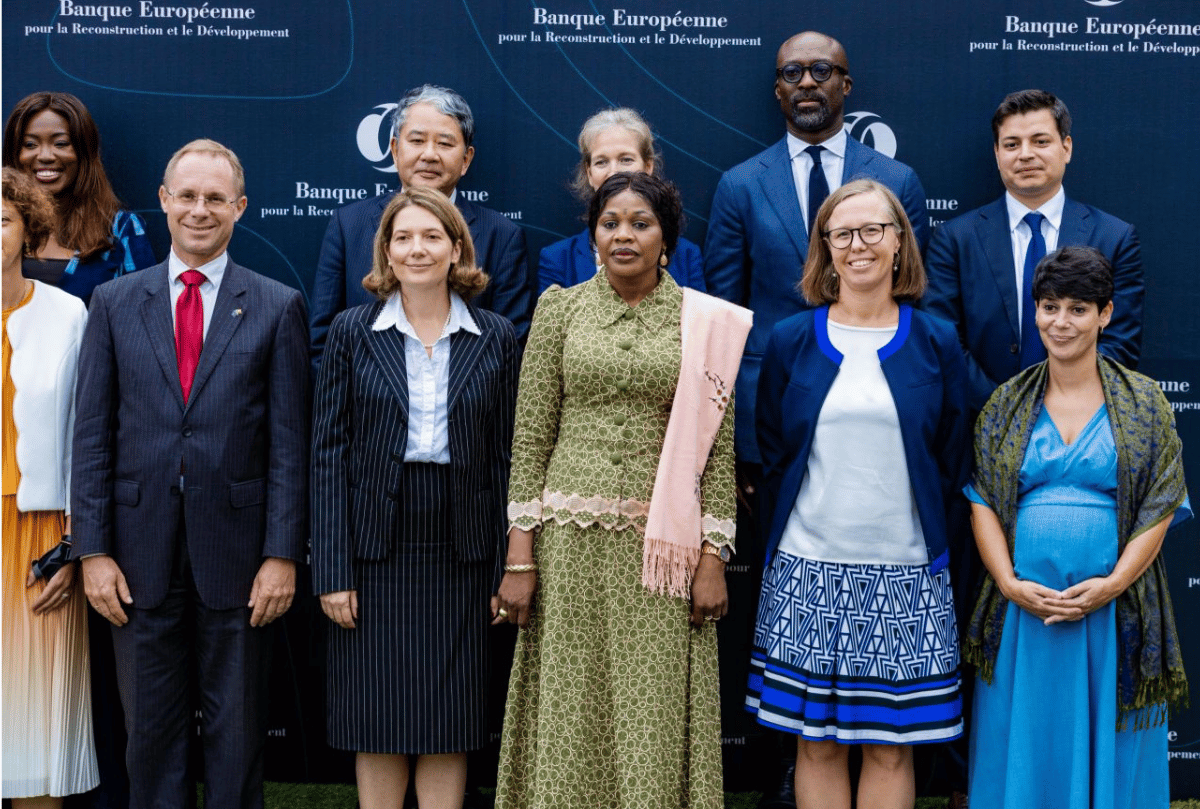
The European Bank for Reconstruction and Development (EBRD) is expanding its support for small and medium-sized enterprises (SMEs) in Benin with an approach that goes beyond lending, seeking to strengthen the management systems, governance, financial practices and digital capabilities that determine whether businesses can attract and effectively use capital.
The programme, launched in Cotonou on September 9, 2026, combines business advisory services with financing instruments and wider support for the institutions that serve the private sector. The move comes as access to finance remains one of the most significant constraints facing businesses in Benin, particularly smaller firms that often lack the financial records, governance structures and planning systems required by banks and investors.
The EBRD said its new SME offer is designed to help businesses become more competitive, investment-ready and resilient. More than 100 representatives from SMEs, mid-cap companies, commercial banks, business associations, chambers of commerce, investors, development finance institutions and public agencies attended the launch in Cotonou.
Under the advisory component, Beninese companies will be able to access local and international consultants, with donor funding helping to cover part of the cost. Depending on the needs of each company, support can include business strategy, organisational structures, corporate governance, financial management, digitalisation and measures to improve energy and resource efficiency.
The underlying proposition is significant for a market where the availability of capital does not necessarily translate into productive investment. Businesses that lack reliable financial statements, formal internal procedures, clear commercial strategies or credible feasibility studies may struggle to convince lenders and investors that additional capital can be deployed effectively.
The World Bank‘s 2024 Enterprise Survey provides a measure of the financing challenge. In Benin, 41.9% of surveyed companies identify access to finance as their biggest obstacle. The survey also shows that 40.1% regard access to finance as a major obstacle and another 13.7% as a very severe obstacle. Among surveyed firms, 29.1% reported having a loan from a financial institution, 6.6% a line of credit, and 3.3% both, although the World Bank cautions that the raw counts should not be interpreted as population estimates.
For smaller enterprises, the challenge is compounded by limited internal capacity. Access to finance can depend not only on whether a viable business exists, but also on whether that business can demonstrate its viability through credible accounts, cash-flow projections, governance arrangements and documented operating procedures.
This makes the EBRD’s focus on bankability particularly relevant. Rather than treating finance as a standalone constraint, the programme seeks to address some of the conditions that determine whether finance can reach productive businesses and support sustainable expansion. The issue is also reflected in research from the World Bank on small firms across developing economies, including Ghana and Nigeria. The research found that stronger business practices in areas such as marketing, record-keeping, financial planning and inventory management are associated with higher productivity, sales and profits, while better practices are also linked to stronger firm survival and growth.
That evidence points to a broader challenge for African SME finance. A company may have a commercially attractive product or a growing customer base but remain difficult to finance if its internal systems have not developed at the same pace as its operations. This is where advisory support can become complementary to lending. For an investor, a better-prepared business can provide clearer information about its financial position, risks, growth strategy and ability to service debt. For the company, stronger systems can improve decision-making and reduce the operational weaknesses that often become more visible during periods of rapid expansion.
The EBRD is therefore pairing its advisory offer with financing instruments. The bank says it will work with financial institutions and corporates to expand financing opportunities for Beninese businesses, including through its Risk Sharing Facility, which allows the EBRD to share risk with partner financial institutions on individual loans to local companies. It will also deploy its Supply Chain Solutions Framework to expand working-capital finance across corporate supply chains.
The approach could be particularly relevant for businesses operating in supply chains where cash-flow constraints arise from the time gap between supplying goods or services and receiving payment. Instruments such as factoring and reverse factoring can provide working capital without relying solely on conventional term lending.
The EBRD is also bringing established SME programmes into Benin, including its Blue Ribbon programme for high-potential companies and Star Venture, which supports innovative and high-growth startups. The bank says its advisory support will also prioritise inclusion, digitalisation and the green transition, including support for women- and youth-led businesses and companies seeking to improve energy and resource efficiency.
The third element of the programme is the broader entrepreneurial ecosystem. This includes working with banks, business associations, support organisations and other institutions involved in SME development. The objective is to strengthen not only individual businesses but also the market around them, including the availability of quality business advisory services.
That ecosystem dimension matters because the shortage of specialised support can itself become a constraint on private-sector development. If entrepreneurs have limited access to credible consultants, financial advisers, market intelligence or investment-preparation services, companies may struggle to progress from an early-stage business proposition to an investable enterprise.
Benin’s Caisse des Dépôts et Consignations has identified a similar gap from the investment side. Investment Director Yémalin Philibert Adankon has argued that the institution encounters entrepreneurs with promising industrial projects but insufficiently developed feasibility studies and business plans to support investment decisions.
The EBRD’s entry into this part of the market also forms part of a broader expansion of its operations in Benin. The country became an EBRD shareholder in 2024 and a country of operation in July 2025. Its first investment in sub-Saharan Africa was a €30 million sovereign loan to Société Béninoise d’Énergie Électrique to support grid expansion and connect 120,000 additional households, or about 600,000 people, to electricity.
The bank has since expanded its activity in areas including municipal infrastructure and private-sector finance. In 2026, it provided a €35.5 million sovereign loan to modernise solid waste management in the Grand Nokoué region, while also beginning work on economic governance and gender standards within the waste-management system.
Its private-sector push is also being supported through financial institutions. The EBRD recently extended a US$20 million trade finance line to Bank of Africa-Benin to support imports, exports and local distribution, accompanied by technical assistance focused on digital transformation and cybersecurity. Taken together, these interventions point to an emerging model in which development finance is being used not only to provide capital but also to strengthen the institutional and operational foundations required for private investment to work.
For Benin, the effectiveness of the SME programme will ultimately depend on whether advisory assistance translates into measurable improvements in productivity, governance, financial transparency and access to capital. The challenge is not simply to finance more companies, but to create a larger pool of businesses capable of absorbing capital, managing growth and competing in regional markets.
For African economies seeking stronger private-sector-led growth, that distinction is increasingly important. Financing can accelerate expansion, but without adequate management systems, financial discipline and governance, additional capital can amplify existing weaknesses. Strengthening bankability before and alongside debt may therefore become an important part of expanding the pipeline of investable SMEs across the continent.
Was this article helpful?
Credit: Source link